Marginal Brackets
How the federal income tax actually charges you: taxable income is cut into slices, and each slice is taxed at its own rate (10% to 37%). A worked 2025 example ($75,750 of wages, $60,000 taxable, $8,114 of tax), the difference between the marginal rate (22%) and the effective rate (about 11–14%), why moving into a higher bracket never lowers take-home pay, and the 2025 and 2026 bracket tables.
- 4 min
- 7 steps
- 3 questions
- Lesson 1 of 9
In this lesson
- The slices
- A worked example
- Marginal and effective
- The myth of moving up a bracket
- The 2026 numbers
- Try it
Picking up where you left off.
The federal income tax isn’t one rate on all your income. It’s a staircase. Your taxable income is cut into slices, and each slice is taxed at the rate for its step. Once you see that, most confusion about “tax brackets” goes away.
The slices
For 2025 (the return filed in spring 2026), a single filer’s brackets are 1:
| Rate | Single: taxable income | Married filing jointly |
|---|---|---|
| 10% | up to $11,925 | up to $23,850 |
| 12% | over $11,925 | over $23,850 |
| 22% | over $48,475 | over $96,950 |
| 24% | over $103,350 | over $206,700 |
| 32% | over $197,300 | over $394,600 |
| 35% | over $250,525 | over $501,050 |
| 37% | over $626,350 | over $751,600 |
The brackets apply to taxable income, which is what’s left after deductions (the next lesson). For 2025 the standard deduction is $15,750 for a single filer and $31,500 for a married couple filing jointly 2.
A worked example
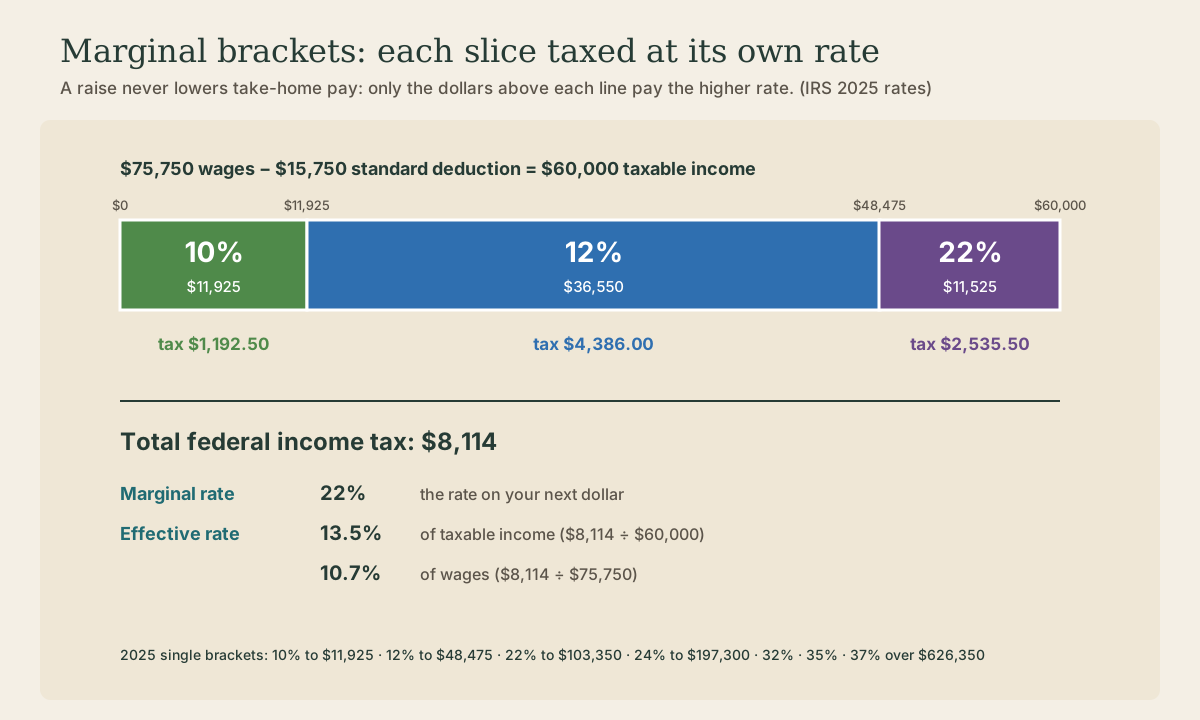
Single, $75,750 of wages, standard deduction:
- Taxable income: $75,750 − $15,750 = $60,000
- 10% on the first $11,925 = $1,192.50
- 12% on the next $36,550 (from $11,925 to $48,475) = $4,386.00
- 22% on the last $11,525 (from $48,475 to $60,000) = $2,535.50
- Total: $8,114
Marginal and effective
Two rates describe that result:
- Marginal rate: 22%. The rate on the next dollar you earn. It’s the one that matters for decisions: an extra $1,000 of overtime costs $220 in federal income tax, and a $1,000 deduction saves $220.
- Effective rate: about 13.5% of taxable income ($8,114 ÷ $60,000), or about 10.7% of wages ($8,114 ÷ $75,750). It’s the share of your income that actually goes to the tax, and it’s always lower than the marginal rate because the bottom slices are taxed lightly.
(Social Security, Medicare, and state tax come on top; they’re in later lessons.)
Quick check
The last slice, above $48,475, is in the 22% bracket. 13.5% is the effective rate.
Quick check
$8,114 ÷ $60,000 ≈ 13.5%.
The myth of moving up a bracket
People sometimes turn down a raise or overtime because it would “put them in a higher bracket.” That never costs money under the federal income tax. Crossing into the 22% bracket only taxes the dollars above the line at 22%; every dollar below stays taxed at 10% or 12%. A $1,000 raise that lands in the 22% bracket adds $220 of tax and leaves you $780 ahead. (Some credits and benefits phase out as income rises, which can create higher effective rates in narrow income ranges, but the brackets themselves never do.)
Quick check
The extra tax is $100 on that slice, so you still keep $780 of the $1,000.
The 2026 numbers
The brackets are indexed to inflation each year. For 2026 (filed in 2027) 2:
- Standard deduction: $16,100 single, $32,200 married filing jointly, $24,150 head of household.
- Single brackets: 10% to $12,400; 12% over $12,400; 22% over $50,400; 24% over $105,700; 32% over $201,775; 35% over $256,225; 37% over $640,600.
- Married filing jointly: 10% to $24,800; 12% over $24,800; 22% over $100,800; 24% over $211,400; 32% over $403,550; 35% over $512,450; 37% over $768,700.
Personal exemptions stay at zero; that change from 2017 is now permanent 2.
Try it
Take last year’s Form 1040, find your taxable income (line 15), and work the slices by hand with the bracket table for that year. Compare with the tax on line 16, then compute your marginal and effective rates. Knowing your marginal rate is the key to judging every deduction, retirement contribution, and side-income decision that follows.
Lesson complete
Nice work.
Sources for this lesson
- 1IRS releases tax inflation adjustments for tax year 2025. Internal Revenue Service. 2024. verifiedTax year 2025 brackets: single 10% to $11,925, 12% over $11,925, 22% over $48,475, 24% over $103,350, 32% over $197,300, 35% over $250,525, 37% over $626,350; married filing jointly 10% to $23,850, 12% over $23,850, 22% over $96,950, 24% over $206,700, 32% over $394,600, 35% over $501,050, 37% over $751,600. Maximum EITC with three or more children $8,046.
- 2IRS releases tax inflation adjustments for tax year 2026, including amendments from the One Big Beautiful Bill. Internal Revenue Service (Rev. Proc. 2025-32). 2025. verifiedStandard deduction: tax year 2025 under OBBB $15,750 single or married filing separately, $31,500 married filing jointly, $23,625 head of household; 2026 $16,100, $32,200, $24,150. 2026 brackets: 10% to $12,400 single ($24,800 MFJ); 12% over $12,400 ($24,800); 22% over $50,400 ($100,800); 24% over $105,700 ($211,400); 32% over $201,775 ($403,550); 35% over $256,225 ($512,450); 37% over $640,600 ($768,700). Personal exemptions remain zero, made permanent by OBBB. 2026 estate basic exclusion $15,000,000; annual gift exclusion $19,000; health FSA $3,400.